Behind Phuket’s glittering beachfront resorts, luxury villas, and seemingly unstoppable tourism developments, a troubling transformation is unfolding across the island’s hospitality property market. While international hotel brands continue expanding and wealthy investors pursue prime coastal real estate, mounting regulatory pressures, weakening hotel revenues, and increasingly fierce competition are creating conditions that could force financially vulnerable accommodation operators to reconsider their futures.
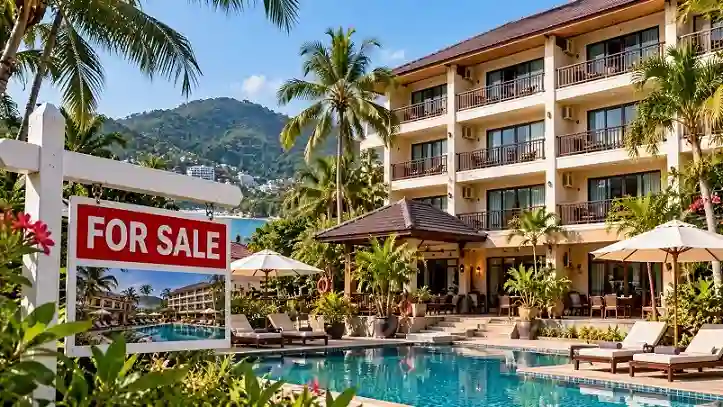
Image Credit: Phuket Hotel News
The emerging pressures examined in this Phuket Hotel News report reveal a widening divide between well-capitalized hospitality groups and smaller independent operators. Although claims of widespread distressed property sales remain difficult to independently verify, recent enforcement operations, declining luxury hotel performance, and longstanding licensing complications suggest that Phuket’s hospitality investment landscape is entering a potentially disruptive period.
According to industry sources, more than 147 hotels are currently being offered for sale across Phuket, ranging from established five-star resorts to smaller independent boutique properties. These listings reportedly include hotels with as few as 30 keys to large hospitality establishments with approximately 320 keys, highlighting the broad spectrum of properties potentially changing ownership.
While not all these sales necessarily involve financially distressed operators, the substantial number of properties reportedly available raises questions about mounting operating costs, intensifying competition, and shifting investor confidence in Phuket’s hospitality sector. The figures have not been independently verified, but industry observers suggest that the growing inventory of hotels being marketed for sale could signal a significant restructuring of the island’s accommodation industry.
Illegal Hotel Crackdown Exposes Vulnerable Investments
One of the most significant developments involves Phuket’s increasingly aggressive enforcement of Thailand’s Hotel Act against unauthorized short-term accommodation businesses.
For years, condominium owners, villa investors, and independent developers have benefited from demand for privately managed vacation accommodations. However, properties designed or registered for residential use cannot automatically operate as commercial hotels.
In June 2026, Thailand’s Department of Provincial Administration launched enforcement operations targeting three allegedly unlicensed accommodation establishments in Karon and Rawai. Investigators found properties accepting tourist bookings and advertising accommodation through online reservation platforms without the necessary hotel licenses.
Further inspections followed in July, including investigations involving condominium developments in Wichit and Kamala.
Most recently, authorities inspected properties in Patong and Ratsada on October 21, following allegations of unauthorized daily rentals and building-use violations. These investigations demonstrate that regulatory enforcement remains an active concern for property investors.
Licensing Problems Threaten Property Values
The consequences extend beyond fines and possible prosecution.
Investors who purchased condominium units or developed villa complexes specifically for short-term tourism may discover that converting their properties into legally compliant accommodation businesses requires substantial expenditure.
Hotel licensing involves building classifications, safety standards, permitted land use, and other regulatory requirements. Properties constructed under residential approvals can face particularly complicated compliance challenges.
Under Thailand’s Hotel Act, unauthorized hotel operations can attract financial penalties, including continuing daily fines until unlawful operations cease.
For owners carrying substantial debt, prolonged interruptions to rental income could create serious financial difficulties.
Nevertheless, regulatory enforcement does not automatically mean that affected properties are being repossessed or sold at distressed prices.
Claims circulating within the investment narrative of discounts reaching 30% to 40% remain unsubstantiated by independently verified transaction data.
Government Licensing Reforms Offer Some Relief
Importantly, Phuket’s licensing situation is not entirely one of regulatory obstruction.
During 2026, authorities accelerated efforts to resolve longstanding hotel licensing applications.
According to an August government announcement, 275 of 392 pending applications had received approval within approximately two months, while another 117 awaited review.
Some applications reportedly dated back to 2018, illustrating the administrative difficulties previously encountered by accommodation operators.
The government’s intervention suggests that authorities recognize the importance of bringing legitimate businesses into the regulated hospitality economy.
However, properties with fundamental construction or land-use violations may still face obstacles that administrative streamlining alone cannot resolve.
Luxury Hotel Revenues Signal Growing Competition
Regulatory enforcement is only one dimension of Phuket’s changing hospitality environment.
Research from Cushman & Wakefield Thailand shows that luxury and upscale hotel performance weakened significantly during the first half of 2026.
Average occupancy declined from 84.1% to 80%, while average daily room rates fell 4% to 6,820 baht.
More significantly, revenue per available room, a crucial profitability indicator known as RevPAR, declined 8.7% to 5,456 baht.
The figures suggest that even established premium properties are experiencing pressure from softer demand and expanding accommodation supply.
Phuket recorded approximately 6.04 million hotel guests during the period, representing a 2.72% annual decline.
International travel uncertainty, higher airfares, and weakening demand from some long-haul markets contributed to the slowdown.
Independent Hotels Face an Unequal Battle
For independent three-star and four-star hotels in established destinations such as Patong, Kata, and Karon, intensifying competition presents another challenge.
Large international operators generally benefit from established reservation networks, customer loyalty programs, centralized purchasing, and sophisticated revenue management systems.
Smaller hotels often lack comparable resources.
When upscale properties reduce room rates to defend occupancy, independent establishments may struggle to maintain their traditional pricing advantage.
Older properties can face additional pressure from renovation requirements, staffing expenses, maintenance costs, and changing guest expectations.
These conditions could encourage some family-owned hotel businesses to explore partnerships, management agreements, or outright property sales.
However, evidence currently available does not establish the scale of any island-wide liquidation wave.
Institutional Investors Could Reshape Phuket
The longer-term implications extend beyond individual hotel owners.
CBRE reported that major publicly listed developers continued leading Phuket’s hotel and condominium development market during the first half of 2026, highlighting the importance of institutional capital in the island’s property sector.
Financially stronger investors may be better positioned to acquire underperforming hospitality assets, fund renovations, and navigate complicated regulatory requirements.
Such acquisitions could eventually accelerate hotel rebranding and consolidation, although the extent of this trend remains uncertain.
For Phuket, the central concern is whether independent operators can remain competitive as hospitality investment becomes increasingly capital-intensive.
A Defining Moment for Phuket Hospitality
Phuket is not experiencing a demonstrated collapse of its tourism industry, but the combination of regulatory enforcement, softer hotel revenues, and expanding competition deserves serious attention. Whether these pressures eventually produce widespread distressed sales or a more orderly restructuring will depend on financing conditions, licensing reforms, visitor demand, and investors’ willingness to support independent hospitality businesses. The island’s next transformation may ultimately be determined as much by who owns its hotels as by how many tourists arrive.